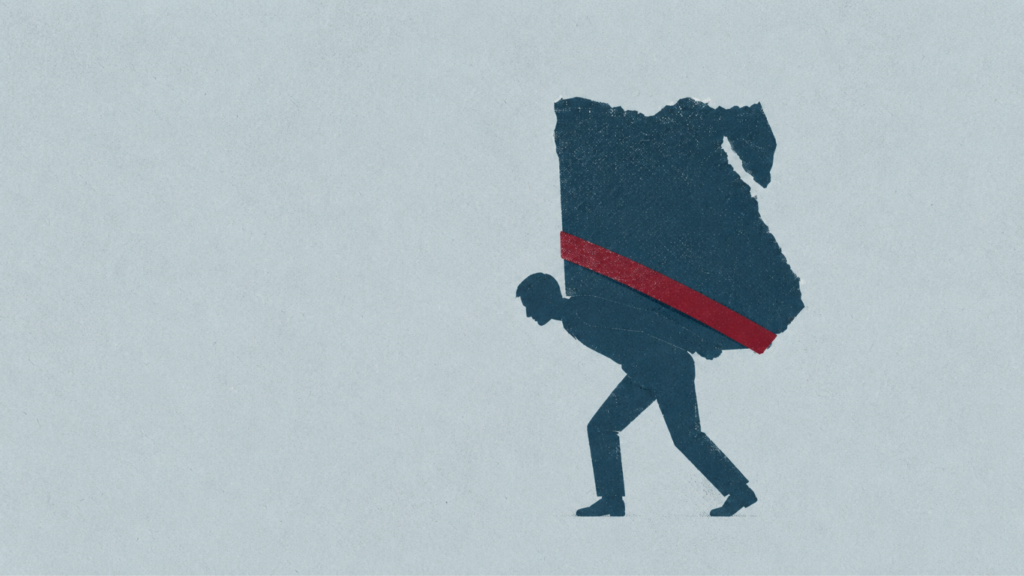
Egypt is preparing for the eighth and final review of its current International Monetary Fund program, scheduled for November 2026 or later. This is the final stage of the Extended Fund Facility (EFF) launched in December 2022, after reviews and amendments expanded the agreed financing.
As the final review approaches, the government has begun preparing for the next phase. President Abdel Fattah El Sisi instructed it to develop a national economic program setting priorities after the IMF reform program ends. In late July 2026, Prime Minister Mostafa Madbouly chaired a meeting on the framework for that program.
The government says the end of the IMF program is a transition to a national program beyond 2026, rather than the end of economic reform. Madbouly said it was preparing a detailed plan through 2030 to sustain growth, lower inflation and unemployment, and strengthen social protection, focusing on industry, tourism, communications and information technology.
The current 46-month program was approved on December 16, 2022, for an initial USD3 billion (SDR2.35 billion). In March 2024, the IMF approved an increase of approximately USD5 billion, bringing agreed financing to about USD8 billion (SDR6.11 billion).
Ten years of IMF borrowing
The 2022 agreement was not the beginning of Egypt’s modern relationship with the IMF. In November 2016, the Fund approved a program worth SDR8.597 billion, approximately USD12 billion, which continued until July 2019 alongside extensive economic measures, notably exchange-rate liberalization.
Following the pandemic, Egypt returned to the Fund in May 2020, receiving approximately USD2.772 billion through the Rapid Financing Instrument. In June, it received SDR3.764 billion under a Stand-By Arrangement, bringing total 2020 financing to around SDR5.8 billion. The December 2022 program started at SDR2.35 billion before rising in March 2024 to SDR6.112 billion, about USD8 billion. Total agreed financing under the four programs since 2016 consequently reached approximately SDR20.51 billion.
In late July, the Fund completed the seventh review alongside the second review under the Resilience and Sustainability Facility. It said Egypt’s macroeconomic stability had improved through faster growth, lower inflation and higher reserves, placing the country in a stronger position to face external shocks. Yet this picture—focused on macroeconomic indicators and the state’s ability to manage external pressure and maintain financial stability—looks different when the effects on citizens are considered.
Economists interviewed in an earlier Zawia3 report argued that better macroeconomic indicators do not necessarily improve living conditions amid rising prices, declining purchasing power, more expensive basic services and growing debt burdens. Resilience should be measured not only by the state’s ability to obtain foreign currency and meet financial obligations, but also by households’ ability to bear crises and reforms and by productive sectors’ capacity to provide jobs and real incomes that sustain living standards.
Alongside borrowing and reform, Egypt’s external debt fluctuated but rose over the longer term. Central Bank of Egypt figures show an increase from USD46.1 billion at the end of fiscal year 2013/14 to USD161.2 billion at the end of 2024/25: about USD115.2 billion, or 250%, over approximately 12 years. The increase continued in the current program’s final phase. The latest available central-bank figures put external debt at approximately USD163.9 billion at the end of the second quarter of 2025/26, nearly USD2.7 billion higher in six months.
How could Egypt move beyond dependence on the IMF?
Egypt’s obligations do not end with the program in 2026. The final review concludes program reviews and disbursements, not outstanding loans. Under the IMF’s projected payments schedule, Egypt will continue repaying through 2046, with expected payments of approximately SDR9.93 billion, including principal, interest, charges and assessments.
The special drawing right is an international reserve asset created by the IMF in 1969. It is not a currency traded like the dollar or euro, but a unit of account for Fund lending and payments. Its daily value is based on five currencies: the US dollar, euro, Chinese renminbi, Japanese yen and British pound. Their weights are reviewed every five years. At the IMF’s official rate on August 18, 2026, one SDR was worth approximately USD1.37, varying daily with the basket’s exchange rates.
Dr. Gouda Abdel Khalek, economics professor and former supply minister, tells Zawia3 that ending repeated dependence on the IMF requires changing the economy’s structure, reducing the need for external borrowing whenever a crisis occurs. He prioritizes curbing monopolies and strengthening competition by activating market regulators and enabling them to confront monopolistic practices, improving production efficiency and domestic producers’ competitiveness.
He calls for greater pound exchange-rate stability and rebuilding production to reduce dependence on imports and foreign inputs. Investment should target strategic gaps and strengthen links between productive sectors so external shocks do not pass directly into the domestic economy. Egypt should make greater use of WTO membership to improve its terms of engagement with foreign markets. Government spending and the administrative apparatus also need review. Moving beyond the Fund means building a more productive, diversified and resilient economy, able to finance needs from its own resources, rather than simply increasing foreign-currency receipts.
Abdel Khalek also links economic reform to radical local-government reform. Without elected local councils, citizens lack a direct mechanism to hold governors, city heads and district leaders accountable, weakening oversight of decisions, spending and services.
Egypt has held no local-council elections since 2011, approximately 15 years ago. These elections constitute the fifth constitutional electoral entitlement since 2013, after the constitutional referendum, presidency and two parliamentary chambers. Executive bodies have performed council duties without elected oversight of governors. The issue has returned as the House of Representatives’ Local Administration Committee discusses a new law to reconstitute councils and hold direct elections from villages and districts to governorates, strengthening decentralization and local participation following presidential instructions to complete this constitutional obligation.
Five pillars of a meaningful national program
According to government announcements, the post-IMF program will set new economic priorities, reduce reliance on borrowing and build internally generated resources. It includes reducing and restructuring external debt, expanding concessional finance and direct investment, accelerating government offerings and supporting industry and agriculture to increase exports and reduce imports. Announced plans also include deeper local manufacturing, industrial localization, greater factory efficiency and capacity utilization, revitalized tourism and technical training linked to labor-market needs. Exchange-rate flexibility is expected to continue alongside monetary policy balancing lower inflation with growth. The government says it will submit the program to public dialogue before formal announcement, with clear targets, measurable indicators and monitoring mechanisms.
Economic researcher Elhami El Merghany proposes pillars for a national program that relies less on external debt and hot-money flows and more on domestic development financing. Speaking to Zawia3, he prioritizes higher domestic savings to fund investment, and greater attention to agriculture and industry as productive sectors that create jobs, add value and generate foreign currency through higher exports and lower imports.
He also proposes tax reform emphasizing direct and progressive taxation of income and wealth and effective property taxes, with less reliance on consumption taxes and VAT. This could increase tax funding of the budget and reduce borrowing. Rather than selling state companies and assets, he proposes operating plans that maximize returns. Projects lacking urgent priority should stop, and no new project should begin without a clear feasibility study specifying economic returns, capital-recovery periods and expected cash flows. These measures, he argues, could increase reliance on domestic resources and direct investment while reducing dependence on loans and hot money.
The real starting point is production, not financial stability alone
Economic and labor researcher Hassan El Barbary tells Zawia3 that the program’s conclusion does not end relations with the IMF: Egypt remains a member and increased its quota over the past two years. He sees a possible attempt to explore a new form of future cooperation, even while moving toward a national program.
A meaningful national program first requires changing the state’s economic objective, he says. After years focused on financial and monetary stability, priority should shift to rebuilding the productive base and production-led growth that generates real resources for debt repayment and development. Manufacturing, agriculture, pharmaceuticals, engineering, electronics and renewables should be rebuilt, each including exportable components to earn foreign currency and components that replace imports and reduce demand for it.
The next phase also needs a redesigned exchange-rate policy rather than flexibility determined by market mechanisms alone, El Barbary argues, as well as tax reform and broader coverage rather than higher burdens on existing taxpayers. He calls for a clear national wages and social-protection program alongside public investment redirected toward public transport, education, health, water, research and digital infrastructure.
He says a national program should include an early-warning system with clear measures of resilience: foreign reserves and their coverage of imports and external obligations, and external-debt trends relative to export receipts. These indicators should underpin clear crisis-response rules, given successive shocks from COVID-19 to the Russia–Ukraine war and regional tensions.
Repeated external shocks have exposed limited shock-absorption capacity, in El Barbary’s assessment. Citizens experienced higher electricity prices and subsidy reductions while the state sought resources to meet financial commitments. A national program therefore requires reconsidering the broad outlines of economic policy, if there is genuine political will to build a more resilient economy.
The payment schedule and experts interviewed show that the IMF program’s end will not free Egypt from debt or external-financing dependence. Fund repayments will continue for years, external debt remains high, and foreign-currency inflows are still needed to meet obligations and finance needs. The real test of the proposed national program is whether it can prevent recurring crises rather than merely manage them; build sectors that generate foreign currency rather than focus on obtaining it to repay debt; expand investment, production and exports instead of borrowing and selling assets; and protect household incomes and purchasing power rather than make families bear reform costs.